Author: Jim Santiago

  • Florida Amendment 3 Passed: What It Means for Your Homestead, Your Taxes, and Your Closing

    Florida voters approved Amendment 3 on November 3, 2026. It got about 62% of the vote, 4,917,482 yes to 3,015,840 no, and it needed 60% to pass (Florida Division of Elections results; unofficial until certified). The amendment is the biggest change to Florida homestead property taxes in years. It takes effect January 1, 2027.

    Here’s what changed, how it plays out at a closing, and how to estimate what it could save you.

    What Amendment 3 Changes

    A bigger homestead exemption for non-school taxes

    • 2027: the first $150,000 of a homestead’s assessed value is exempt from all non-school property taxes (county, city, and most special districts).
    • 2028: that rises to $250,000.
    • 2029 and after: the amount is adjusted for inflation.

    The new amount replaces the current non-school exemption; it doesn’t stack on top of it. For 2026 the current maximum homestead exemption is $51,411, per the Florida Department of Revenue as reported by NBC 6.

    School taxes stay the same

    The exemption against school district taxes stays at $25,000. School taxes are a large share of most Florida tax bills, so your real savings will be smaller than the headline numbers suggest.

    Non-homestead cap drops from 10% to 5%

    For non-homestead property, including rentals, second homes, and commercial property, the yearly cap on assessed value increases drops from 10% to 5%. It doesn’t apply to school district taxes.

    Limits on how local governments spend property tax money

    The amendment also limits what counties and cities can spend property tax revenue on. That matters for local budgets, but it doesn’t change anything at the closing table, so we won’t cover it here.

    The New-Resident Rule: The Date That Matters Is December 31, 2026

    This is the part buyers relocating to Florida need to understand. According to the amendment’s ballot summary and the Miami-Dade County Amendment 3 page:

    • If you are a Florida resident by December 31, 2026, you’re eligible for the larger exemption once you qualify for homestead.
    • If you aren’t a Florida resident on December 31, 2026, you start with the existing exemption, up to $50,000, and the larger exemption begins with your fifth year of homestead exemption.

    The ballot language says the rule applies “to the extent permitted by the U.S. Constitution,” so it could be challenged or clarified later. If you’re moving to Florida and your timing is close to the end of the year, ask your county property appraiser how the rule applies to you.

    What It Means at Closing: Tax Prorations

    At a typical Florida closing, property taxes for the year are prorated between buyer and seller. Florida taxes are paid in arrears: the 2026 bill comes out in November 2026 and covers the whole calendar year. Here’s how that works out:

    • Closings in 2026 are prorated on 2026 taxes, either the actual bill or an estimate based on the prior year if the bill isn’t out yet. Amendment 3 doesn’t change 2026 bills.
    • Closings in 2027 will often be prorated on the 2026 bill because the 2027 bill won’t be issued until late 2027. Since the new exemption should lower 2027 non-school taxes for qualifying homesteads, estimating from the 2026 bill could overstate what’s owed. Your closing agent and the parties may agree on how to handle the estimate. Ask early.
    • The seller’s exemption doesn’t transfer to the buyer. When a home sells, the property appraiser generally reassesses it at market value the next January 1, and the seller’s Save Our Homes cap goes away. A buyer’s first full tax bill can be much higher than the seller’s, even with the bigger exemption.

    We see that last point surprise buyers more than anything else. Don’t budget off the seller’s current tax bill. Our Broward County closing costs guide explains how prorations and other line items show up on your closing statement.

    After You Buy: File for Homestead and Portability

    Amendment 3 doesn’t apply automatically to a new purchase. You still have to qualify and apply:

    1. Own the home and make it your permanent residence by January 1 of the tax year.
    2. File with your county property appraiser by March 1. Most counties take online applications.
    3. Ask about portability. If you’re moving from one Florida homestead to another, you may be able to transfer up to $500,000 of your Save Our Homes benefit to the new home. The deadline for that filing is also March 1.

    Once granted, a homestead exemption generally renews automatically each year. We haven’t seen anything saying current homesteaders need to reapply for the larger amount, but watch for notices from your property appraiser.

    Investors and Second-Home Owners: The 5% Cap

    If you own rental property, a vacation home, or commercial property, you don’t get the homestead exemption. Starting in 2027, though, the yearly increase in your assessed value for non-school taxes is capped at 5% instead of 10%.

    The same reset applies when non-homestead property sells: it’s reassessed at market value, and the cap starts over from there. If you’re buying investment property, budget for taxes on market value, not the seller’s capped value.

    How to Estimate Your Savings

    The quick shortcut (Florida TaxWatch)

    Florida TaxWatch’s property tax resource center gives a simple formula. Find your non-school millage on your tax bill (everything except the school board lines), then:

    • 2027 savings is about your non-school millage x $98.59
    • 2028 savings is about your non-school millage x $198.59

    Those figures are the difference between the new exemption and today’s maximum of $51,411, divided by 1,000. Example: at 10.5 non-school mills, that’s roughly $1,035 in 2027 and $2,085 in 2028.

    Online calculators

    Every calculator is an estimate. None of them is tax advice, and your actual bill depends on next year’s assessed values and the millage rates local governments set in 2027 and 2028.

    Fort Lauderdale and Broward County

    When we checked, we didn’t find an Amendment 3 calculator on the Broward County Property Appraiser site. Broward owners can still use BCPA to look up their assessed value and the millage on their tax bill, then use the shortcut above or the My Exemption Check tool.

    Worked example (example rate, not your actual rate): Say a Broward homestead has a $400,000 assessed value and a non-school millage of 13.0 mills. Your actual non-school millage depends on your city and taxing districts, so check your own bill.

    • 2026 non-school taxable value: $400,000 – $51,411 = $348,589, or about $4,532 in non-school taxes
    • 2027: $400,000 – $150,000 = $250,000, or about $3,250 (about $1,282 less)
    • 2028: $400,000 – $250,000 = $150,000, or about $1,950 (about $2,582 less)

    School taxes would be about the same in every year. This example holds the assessed value flat; in practice it can still rise by up to the Save Our Homes cap each year.

    If you’re buying or selling in Fort Lauderdale or anywhere in Broward, our Fort Lauderdale title company and Broward County title company teams can walk you through the tax prorations on your deal.

    Frequently Asked Questions

    Does Amendment 3 lower my November 2026 tax bill?
    No. The amendment takes effect January 1, 2027. The first bills with the larger exemption will be the 2027 bills, mailed around November 2027.

    I’m moving to Florida in 2027. Do I get the $150,000 exemption?
    Under the amendment, people who aren’t Florida residents on December 31, 2026 start with the existing exemption, up to $50,000, and get the larger exemption starting in their fifth year of homestead exemption. Confirm your situation with your county property appraiser.

    Does the bigger exemption reduce school taxes?
    No. The school tax exemption stays at $25,000. The bigger exemption applies only to non-school taxes.

    Will my taxes stay the same as the seller’s after I buy?
    Usually not. The home is generally reassessed at market value the January 1 after the sale, and the seller’s Save Our Homes cap doesn’t transfer. File for your own homestead exemption by March 1, and ask about portability if you’re moving from another Florida homestead.

    How are taxes prorated if I close in 2027?
    Florida taxes are paid in arrears, so a 2027 closing is often prorated on an estimate, usually based on the 2026 bill. Because the new exemption may lower 2027 taxes, ask your closing agent how the estimate will be handled.

    Plan Your Closing With Us

    Florida’s Best Title Company (Independent Title of Fort Lauderdale) handles residential and investor real estate closings across Florida, in person or by remote online closing. Open title with plenty of time before closing so there’s room to sort out tax prorations, estoppels, and payoffs. Our Florida closing timeline shows what to expect.

    Call (954) 493-8288 or visit us at 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306.

    Disclaimer: This article is for general information only and is not legal or tax advice. Amendment 3 may be implemented through future legislation and property appraiser guidance, and the details may change. Tax estimates are illustrations only. Consult a qualified attorney, tax professional, or your county property appraiser about your situation.
  • Can You Close on a Florida Home Remotely? How Remote Online Closings Work

    Yes, you can close on a Florida home without being in the room. Florida law allows remote online notarization (RON), so buyers and sellers can sign closing documents by live video from almost anywhere, and a title company can also send a mail-away package for you to sign in front of a local notary. The catch is that the lender, if there is one, has to allow the method you want, so ask early.

    What is a remote online closing in Florida?

    A remote online closing means you sign your closing documents electronically on a secure video session with a Florida online notary instead of sitting at a closing table. Florida authorized remote online notarization under Chapter 117 of the Florida Statutes starting in 2020. During the session, your identity is verified, you sign on screen, and the whole session is recorded and stored by the notary platform. Your deed or mortgage then gets recorded with the county the same way a paper-signed one does.

    Who can close remotely?

    Remote closings work well for:

    • Out-of-state and seasonal owners selling a Florida condo or house
    • Buyers relocating to Florida who can’t fly in on closing day
    • Investors closing several files at once
    • Sellers who’ve already moved, or are traveling, when the deal closes
    • Many signers living outside the U.S., depending on the documents and the lender

    Remote online notarization vs. mail-away vs. power of attorney

    There are three common ways to close without being there:

    • Remote online notarization (RON): You sign electronically on a live video call with a Florida online notary. It’s the fastest option, and documents can be recorded the same day. Florida deeds need two witnesses, and RON platforms can provide remote witnesses for the session.
    • Mail-away closing: The title company sends (or emails) your signing package, you sign in front of a notary where you live, with witnesses for the deed, and you overnight the originals back. It takes a few extra days for shipping, so build that into the closing date.
    • Power of attorney: Someone you trust signs for you. The power of attorney has to meet Florida requirements and be approved by the title company and lender before closing, so send it in well ahead of time.

    When a remote closing might not work

    Not every file can close by RON. Some lenders and loan programs still require an in-person or wet-ink signing for the mortgage documents. Some signers can’t pass the online identity check, for example without a qualifying government ID or U.S. credit history. Certain situations, like a signer who needs extra protection or help understanding documents, may call for an in-person signing. If you’re planning a remote closing, tell your title company and your lender with plenty of time before closing so there’s room to switch to a mail-away or mobile notary if needed.

    How to protect your money in a remote closing

    Remote closings rely on email and electronic wires, which is exactly what wire fraud scammers target. Florida buyers have lost closing funds to fake wiring instructions sent from look-alike email addresses. Before you wire anything:

    • Call your title company at a phone number you already know, not one from the email, to confirm the wiring instructions
    • Treat any “updated” or “changed” wiring instructions as a red flag
    • Never send account numbers or passwords by email
    • Call again after sending the wire to confirm it arrived

    A legitimate title company will never be annoyed that you called to double-check.

    Fort Lauderdale and Broward County

    Broward has a lot of out-of-state and seasonal condo owners, so remote and mail-away closings are routine here, especially for sellers who spend most of the year up north. Broward condo files still need the estoppel certificate and any association approval on time, and none of that changes because you’re signing remotely. Florida’s Best Title Company (Independent Title of Fort Lauderdale) handles remote online, mail-away, and in-person closings statewide from our office at 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306.

    Frequently asked questions

    Can I close on a house in Florida without being there?
    Yes. Florida allows remote online notarization, so you can sign closing documents by secure live video. You can also do a mail-away closing with a local notary or, in some cases, use a power of attorney.

    Is remote online notarization legal for Florida real estate closings?
    Yes. Florida authorized remote online notarization under Chapter 117 of the Florida Statutes, and deeds and mortgages signed this way can be recorded in Florida counties. Your lender still has to allow it for the mortgage documents.

    Do Florida deeds need witnesses in a remote closing?
    Yes. Florida deeds require two witnesses. In a remote online closing, witnesses can take part through the online notary platform. In a mail-away closing, you sign with witnesses in front of your local notary.

    Can I close remotely if I live outside the United States?
    Often, yes, but it depends on the documents, the lender, and whether you can complete the identity check. Some international signers use a mail-away package signed at a U.S. embassy or consulate instead. Ask your title company early.

    How do I avoid wire fraud when closing remotely?
    Always confirm wiring instructions by calling your title company at a phone number you already trust, never one from an email. Treat any change in wiring instructions as a warning sign.

    Related reading: the Florida closing process, Broward County closing costs, and a seller’s guide to choosing a title company.


    Selling or buying from out of state? Call Florida’s Best Title Company at (954) 493-8288 to set up a remote or mail-away closing.

    This article is general information only and is not legal advice. Every transaction is different. For advice about your specific situation, talk with a Florida real estate attorney.

  • Title Company vs. Real Estate Attorney in Florida: Who Do You Need to Close?

    You can always have a Florida real estate attorney represent you in your transaction, and choosing a title company to close doesn’t change that.

    In Florida, you do not need a real estate attorney to close on a home. A licensed title company can search the title, issue title insurance, hold escrow, prepare the settlement statement, and run the closing, and that’s how most Florida residential sales and refinances close. What a title company can’t do is give you legal advice, so if your deal has a legal question in it, that’s when you bring in a Florida real estate attorney, often alongside the title company rather than instead of it.

    Is Florida an attorney-closing state?

    No. Some states require a lawyer to conduct or supervise every closing. Florida isn’t one of them. Florida closings are commonly handled by title agencies licensed through the Florida Department of Financial Services, and Florida attorneys can also act as title agents and close files themselves. Either one can close your transaction; the buyer, seller, or lender just needs someone qualified to insure and settle it.

    What a Florida title company handles

    A title company’s job is to make sure the property can transfer cleanly and that the money moves correctly. On a typical file that means:

    • Searching public records for liens, judgments, open permits, unpaid taxes, and ownership gaps
    • Issuing the title commitment and, after closing, the owner’s and lender’s title insurance policies
    • Ordering payoffs on existing mortgages and, for condos and HOA homes, the estoppel certificate
    • Holding deposits and closing funds in escrow
    • Preparing the settlement statement and coordinating with the lender’s closing disclosure
    • Conducting the signing, in person, by mobile notary, or by remote online notarization
    • Recording the deed and mortgage and paying off everyone who’s owed

    What only an attorney can do

    Title agents aren’t allowed to give legal advice or represent one side against the other. You’ll want a Florida real estate attorney when you need someone in your corner on a legal question, for example:

    • Probate, estate, or heirs’ property, where someone has to establish who can legally sell
    • Quiet title actions, boundary disputes, or a title defect that needs a court fix
    • Divorce, partition, or co-owner disagreements over a sale
    • Complicated entity, trust, or LLC ownership questions
    • Foreclosure, short sale, or lien negotiations that turn into a dispute
    • Any time you want advice about your rights or obligations in the deal

    Do title insurance rates change if an attorney closes?

    The title insurance premium itself doesn’t. Florida sets title insurance premium rates by rule, so the premium on the same policy is the same whether a title company or an attorney-agent issues it. What can differ are the settlement fees, search fees, and any separate legal fees an attorney charges for representation. Ask for an itemized quote up front so you’re comparing the same line items. Our closing cost guide breaks those line items down.

    When it makes sense to use both

    Plenty of Florida deals use a title company to close and an attorney for advice on one specific issue. A common example: the title search turns up an old lien or an estate issue. The title company identifies the problem and tells you what it needs to insure over it or clear it, and an attorney handles the legal work to fix it. The closing still happens at the title company. Opening title with plenty of time before closing gives everyone room to spot these issues early instead of the week of closing (see our Florida closing timeline).

    Fort Lauderdale and Broward County

    In Broward, most residential closings, including condo and HOA files, close through title companies, and buyers and sellers can choose who handles it. Broward condo files often hinge on the estoppel, association approval, and recorded documents more than on anything that needs a lawyer. Florida’s Best Title Company (Independent Title of Fort Lauderdale) closes files statewide from our Fort Lauderdale office at 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306, and we’ll tell you plainly when something on your file is a question for an attorney.

    Frequently asked questions

    Do I need a lawyer to buy a house in Florida?
    No. Florida doesn’t require an attorney for a residential closing. A licensed title company can handle the title search, title insurance, escrow, and closing. You can still hire an attorney if you want legal advice on your deal.

    Can a title company give me legal advice?
    No. Title agents can explain the closing process, the title commitment, and what’s needed to close, but they can’t advise you on your legal rights. For that, talk to a Florida real estate attorney.

    Is title insurance cheaper if an attorney closes my deal in Florida?
    No. Florida title insurance premiums are set by state rule, so the premium is the same either way. Settlement fees and any attorney fees for representation are where costs can differ.

    Who chooses the title company in a Florida closing?
    It depends on the deal and the county’s custom, and buyers and sellers can choose. Florida’s Best Title Company closes for buyers, sellers, lenders, and investors across Florida.

    When should I hire a real estate attorney in Florida?
    Consider one for probate or heirs’ property, title defects that need a court fix, ownership disputes, divorce or partition sales, or any time you need advice on your rights. Many of these files still close at a title company.


    Ready to open a file or get a quote? Call Florida’s Best Title Company at (954) 493-8288.

    This article is general information only and is not legal advice. Every transaction is different. For advice about your specific situation, talk with a Florida real estate attorney.

  • What Happens If a Title Search Finds a Lien in Florida?

    If a title search finds a lien on a Florida property, the deal usually isn’t dead. In most cases the title company gets a written payoff or release, the lien is paid from the seller’s proceeds at closing, and the release is recorded so the buyer gets clear title.

    What changes is the timeline. A simple mortgage payoff takes a few days, but an old judgment, an unpaid contractor’s lien, or a code enforcement fine can take weeks to sort out. That’s why it pays to open title with plenty of time before closing, so there’s room to clear problems before closing day.

    What counts as a lien?

    A lien is a legal claim against a property for money owed. Until it’s paid, released, or otherwise resolved, it “clouds” title, and a title insurer generally won’t issue a clean policy over it. Common liens that show up on Florida title searches include:

    • Existing mortgages and HELOCs (including old ones that were paid but never formally satisfied)
    • Judgment liens from lawsuits, recorded in the county Official Records
    • Construction liens from contractors, subcontractors, or suppliers who say they weren’t paid
    • Condo or HOA claims of lien for unpaid assessments
    • Code enforcement and municipal liens from your city or county
    • Federal tax liens from the IRS
    • Child support or other state liens

    How each type of lien usually gets cleared

    Mortgages and HELOCs

    The title company orders a payoff (estoppel) letter from the lender and pays it from the seller’s proceeds at closing. Under Florida Statutes s. 701.04, the lender must then record a satisfaction. If an old mortgage shows up that the seller already paid off, the title company tracks down proof of payment and a recorded satisfaction. Open HELOCs also need to be frozen and closed, not just paid down to zero.

    Judgment liens

    A certified copy of a judgment recorded in a county’s Official Records creates a lien on the debtor’s real property in that county under s. 55.10. The usual fix is to get a payoff from the creditor’s attorney, pay it at closing, and record a satisfaction. Common names cause false hits, so a title company may ask for a “same-name” or identity affidavit to show the judgment belongs to someone else. If the property is the seller’s Florida homestead, judgment liens generally don’t attach to it, but the title underwriter will usually still want homestead documentation before ignoring the judgment.

    Construction (contractor) liens

    This came up on X recently: can a contractor really lien a Florida house over a small unpaid bill? Yes. A properly recorded construction lien under Chapter 713 can cloud title for a small amount, and homestead doesn’t protect against it. But it doesn’t last forever. Under s. 713.22, the lienor generally has one year from recording to sue to enforce it, and an owner can shorten that window to 60 days by recording a notice of contest. At closing, the options are usually:

    • Pay the contractor and record a release
    • Transfer the lien to a bond or cash deposit (s. 713.24) so the property is released while the dispute continues
    • Confirm the lien has expired under the statute, with the underwriter’s sign-off

    Condo and HOA liens

    Unpaid assessments can lead to a recorded claim of lien. The association’s estoppel certificate shows what’s owed, and the title company pays it at closing so the buyer doesn’t inherit the balance. More on that process: Florida Condo & HOA Estoppel Certificates at Closing.

    Code enforcement and municipal liens

    Some city and county liens (code fines, unpaid utilities, open permits) don’t always show up in a standard Official Records search, which is why many Florida closings include a separate municipal lien search. Code fines can sometimes be reduced through your city or county’s lien-reduction or mitigation process, but that takes time, so start early. Open permits may need to be closed out with the local building department before the buyer or lender will proceed.

    IRS tax liens

    A federal tax lien can be paid from proceeds with a payoff from the IRS, or the seller can apply for a certificate of discharge for that property. These take weeks, so flag them immediately.

    What if the lien is bigger than the seller’s equity?

    If the liens add up to more than the sale price minus costs, the seller has to bring money to closing, negotiate a reduced payoff with the lienholder, or, with mortgage debt, explore a short sale with lender approval. A title company can lay out the numbers, but the negotiation belongs to the seller and their attorney or agent.

    Who pays to clear the lien?

    Usually the seller, since the seller is the one transferring clear title. Payoffs come out of the seller’s side of the closing statement. Buyers should never assume an unknown lien is “someone else’s problem,” which is exactly why lenders require a lender’s title policy and why an owner’s policy is worth having. See Florida Title Insurance Explained.

    How a lien affects your closing timeline

    Lien type Typical clearing effort
    Mortgage / HELOC payoff Days
    Condo / HOA balance via estoppel Days to about 2 weeks
    Judgment with responsive creditor 1-3 weeks
    Construction lien (pay, bond, or contest) 1-4+ weeks
    Code enforcement fine reduction Weeks to months
    IRS discharge Several weeks or more

    These are general ranges, not promises; every lienholder moves at its own speed. Full timeline context is in How Long Does a Florida Closing Take? House vs. Condo.

    Tips for Florida sellers and agents

    1. Open title with plenty of time before closing.
    2. Tell your title company about any known judgments, unpaid contractors, code violations, or past-due HOA dues up front.
    3. Have old payoff letters or satisfaction records ready if you’ve paid off past mortgages.
    4. Don’t pay a lienholder directly without a written payoff and release; let the closer handle it so the release gets recorded.
    5. If a contractor lien is disputed, talk to a Florida attorney early about bonding or contesting it.

    Liens on Fort Lauderdale/Broward properties

    Broward County is split among dozens of cities and towns, and code fines, utility balances, and open permits are tracked by each city, so a municipal lien search on a Broward property needs to reach the right city as well as the county. Broward also has a high volume of condos and HOAs, which makes association estoppels and claims of lien a regular part of local closings. Recorded mortgages, judgments, construction liens, and satisfactions are searched in the Broward County Official Records. Starting these searches early gives the most time to clear anything they turn up.

    Need a title search on a Florida property?

    Florida’s Best Title Company (Independent Title of Fort Lauderdale) runs title searches, municipal lien searches, and payoffs for sales and refinances, and we close across Florida. Start a closing cost quote with our TitleQuote calculator, or call (954) 493-8288. Our office is at 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306. Sellers can also read our Broward seller’s guide to choosing a title company and our Broward closing costs guide.

    Frequently Asked Questions

    What happens if a title search finds a lien in Florida?
    The title company identifies the lienholder, gets a written payoff or release, and usually pays the lien from the seller’s proceeds at closing. Other options include bonding off a construction lien, confirming a lien has expired, or documenting that a judgment doesn’t attach to homestead.

    Can I sell my house in Florida with a lien on it?
    Usually yes, as long as there’s enough equity to pay the lien at closing or the lien is released or resolved another way before the buyer’s title policy is issued.

    Can a contractor put a lien on my Florida house for a small amount?
    Yes. A properly recorded construction lien can cloud title for any amount, and homestead doesn’t protect against it. The lienor generally must sue within one year of recording, or within 60 days if the owner records a notice of contest.

    Who pays off liens at a Florida closing?
    Typically the seller, through deductions on the seller’s side of the closing statement, because the seller is responsible for delivering clear title.

    Why do Florida closings often include a municipal lien search?
    Some city and county liens, like code fines, unpaid utilities, and open permits, may not appear in a standard Official Records search. A municipal lien search helps catch them before closing.

    This article is for general information only and is not legal, tax, or financial advice. Lien rules, deadlines, and underwriting requirements can change, and every property and transaction is different. Consult a Florida real estate attorney about your situation.

  • Best Title Company in Broward County for Home Sellers: A Seller’s Guide

    The best title company in Broward County for home sellers is the one that clears your payoffs, liens, and association estoppels early, keeps settlement fees transparent, and gets you to the closing table on time. In Fort Lauderdale/Broward, the title insurance premium itself is set by the state, so what you should compare is service, search and settlement fees, and how well the closer handles seller-side work.

    Who selects the closing agent and who pays the owner’s policy depends on your purchase contract. Local custom in Broward often has the buyer choosing and paying for the owner’s policy, but that is custom, not law, and the parties can agree otherwise. Either way, the title company still controls much of what you feel as a seller: when your mortgage is paid off, when association balances are confirmed, when open items get cleared, and how cleanly your net proceeds arrive.

    Why sellers should care who closes

    Your title company does far more than print a policy. On a Fort Lauderdale/Broward sale it typically:

    • Runs the title search and flags liens, judgments, old mortgages, and probate or divorce issues
    • Orders mortgage payoffs and association estoppel certificates
    • Coordinates municipal and open-permit searches where needed
    • Prepares the closing statement and holds funds in escrow
    • Records the deed and pays off what must be paid at closing
    • Wires or cuts your net proceeds after everything clears

    A slow or unresponsive closer can delay your move, your next purchase, or the release of your proceeds. A strong one catches problems weeks earlier.

    Doc stamps: the big seller-side cost

    In Broward, sellers customarily pay the Florida documentary stamp tax on the deed at $0.70 per $100 of the sale price (Florida Department of Revenue). On a $400,000 sale, that is $2,800. That tax is set by the state, not by your title company. For a full cost picture, see How Much Are Closing Costs in Broward County.

    The title premium is the same everywhere

    Florida title insurance premiums are promulgated under Fla. Admin. Code Rule 69O-186.003. Every licensed title company charges the same premium for the same coverage amount. On a $400,000 owner’s policy, that is about $2,075 ($5.75 per $1,000 on the first $100,000, then $5.00 per $1,000 up to $1 million).

    So “cheapest premium” is not a useful shopping question in Florida. What varies-and what sellers should ask for in writing-are settlement (closing) fees, title search and exam charges, municipal lien and open-permit search fees, courier or e-recording charges, and how payoffs and estoppels are handled. More on what the policy covers is in Florida Title Insurance Explained. Buyers and refinance borrowers have shopping rights too; see You Can Choose Your Title Company in Florida.

    What to look for in a seller-friendly Broward title company

    1. Clear, written settlement and search fees

    Ask for a fee sheet that lists every non-premium title charge. Compare those lines, not the state-set premium.

    2. Fast payoff and estoppel handling

    Sellers need the existing mortgage paid off correctly and, for condo or HOA properties, a current estoppel that shows assessments, transfers, and any special amounts due. Delayed estoppels are one of the most common reasons Fort Lauderdale/Broward closings slip. Read Florida Condo & HOA Estoppel Certificates at Closing.

    3. Lien, judgment, and open-permit searches

    A thorough search finds recorded liens and judgments early. Many deals also need a municipal or open-permit check so old building permits or code items do not surprise anyone on closing day. Ask how the company handles those searches and how they communicate findings to your agent.

    4. Condo and HOA experience

    Broward has a large share of condos, co-ops, and planned communities. A closer who regularly orders estoppels, reads association questionnaires, and knows common transfer requirements will save you days.

    5. Responsiveness and a real local office

    You want a named closer who returns calls and emails the same day, and a Fort Lauderdale/Broward office you can reach when something urgent comes up. Florida’s Best Title Company (Independent Title of Fort Lauderdale) is at 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306, (954) 493-8288.

    6. Remote and mail-away options for out-of-town sellers

    If you already moved, or you travel for work, ask about remote online notarization where allowed, mobile notary, or mail-away packages. A seller who can sign from another state should not have to fly back just to close.

    7. Clean escrow and recording practices

    Confirm that funds sit in a proper escrow account, that payoffs go out promptly after closing, and that the deed is recorded correctly with Broward County. That is how your net proceeds and your buyer’s ownership stay clean.

    How long a seller should expect

    House closings and condo closings often run on different clocks because associations add estoppel and approval steps. Timeline details are in How Long Does a Florida Closing Take? House vs. Condo. Opening title with plenty of time before closing gives the closer time to clear liens and order estoppels before the last week.

    A simple seller checklist

    1. Ask who will be your closer and how to reach them directly.
    2. Get a written list of settlement, search, and recording-related fees.
    3. Confirm they will order mortgage payoffs and association estoppels promptly.
    4. Ask how they handle municipal or open-permit searches on your property type.
    5. If you are out of town, ask about remote, mobile, or mail-away signing.
    6. Tell your real estate agent early which title company you prefer, so the file is opened right away.

    Get a seller-side quote for your Fort Lauderdale/Broward sale

    Start a closing cost quote with our TitleQuote calculator, or call Florida’s Best Title Company (Independent Title of Fort Lauderdale) at (954) 493-8288. We close residential sales across Fort Lauderdale/Broward from our office at 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306.

    FAQ

    What is the best title company in Broward County for home sellers?

    Look for a Fort Lauderdale/Broward closer that clears payoffs and estoppels early, quotes settlement and search fees in writing, has condo/HOA experience, and offers remote or mail-away signing when you need it. The title premium is the same everywhere in Florida.

    Do home sellers in Broward choose the title company?

    It depends on the purchase contract. Broward custom often has the buyer selecting the closing agent and paying the owner’s policy, but the parties can agree to a different arrangement. Sellers still benefit from a strong, responsive title team either way.

    Are title insurance premiums cheaper at some Broward title companies?

    No. Florida sets the premium by state rule. Compare settlement fees, search fees, and service instead.

    What closing costs do sellers usually pay in Fort Lauderdale/Broward?

    Deed documentary stamps at $0.70 per $100 of the sale price are usually the largest seller-side tax. Settlement allocations, estoppel fees, and other items depend on the contract and the property. See our [Broward closing costs guide](https://www.indytitleftl.com/blog/broward-county-closing-costs/).

    Can I close remotely if I already left Florida?

    Often yes. Ask your title company about remote online notarization where allowed, a mobile notary, or a mail-away package so you do not have to return in person.

    This article is for general information only and is not legal, tax, or financial advice. Rates and customs can change, and every transaction is different. Consult a Florida real estate attorney or tax professional about your situation.

  • How Much Are Closing Costs in Broward County, Florida?

    In Fort Lauderdale/Broward, buyers usually pay about 2% to 5% of the purchase price in closing costs, with financed buyers at the higher end because of lender fees and Florida’s mortgage taxes. Sellers usually pay about 1% to 3% before real estate commission (roughly 6% to 10% if commissions are included), and the biggest seller item is the state documentary stamp tax on the deed.

    The exact number depends on the price, whether there’s a loan, and whether the property is in a condo or HOA. Here’s what goes into it.

    Florida doc stamps on the deed: $0.70 per $100

    Florida charges documentary stamp tax on the deed at $0.70 per $100 of the sale price in every county except Miami-Dade (Florida Department of Revenue). In Broward, the seller customarily pays it.

    • Example: $400,000 sale = $2,800 in deed doc stamps.

    Mortgage doc stamps ($0.35 per $100) and intangible tax (0.2%)

    If the buyer has a loan, two state taxes apply to the new mortgage, and the buyer normally pays both:

    Example: a $320,000 loan = $1,120 in mortgage stamps + $640 intangible tax = $1,760.

    Title insurance: the premium is set by the state

    Florida title insurance premiums are promulgated, which means the state sets the rate and every title company charges the same premium for the same coverage (Fla. Admin. Code Rule 69O-186.003). The rate is $5.75 per $1,000 for the first $100,000 of coverage and $5.00 per $1,000 from $100,000 to $1 million. On a $400,000 owner’s policy that comes to about $2,075. When there’s a loan, the lender’s policy issued at the same time costs much less.

    Who pays the owner’s policy varies by county and by contract. Read Florida Title Insurance Explained for owner’s vs. lender’s policies and endorsements.

    Settlement, title search, and closing fees

    These fees are not set by the state, so this is where title companies really differ: the settlement (closing) fee, title search, exam, lien and municipal searches, and courier or e-recording charges. Get these in writing before you choose. You can usually pick your own title company; see You Can Choose Your Title Company in Florida.

    Recording fees

    The Broward County Clerk/Records division charges recording fees for the deed and the mortgage, which by state statute are $10 for the first page and $8.50 for each additional page. A typical purchase runs from under $100 to a couple hundred dollars, depending on page counts.

    Estoppel, HOA, and condo association fees

    If the property is in an HOA or condo, the association charges an estoppel certificate fee to confirm what’s owed, and some charge capital contributions or transfer/application fees. Sellers usually pay for the estoppel, and buyers usually pay the application fees. See our estoppel certificate guide.

    Lender fees

    For financed buyers: origination or points, underwriting, appraisal, credit report, flood certification, and similar charges. Your Loan Estimate lists them, and they’re often the biggest buyer-side cost after the state taxes.

    Prepaids and escrows

    Lenders collect prepaid daily interest and set up an escrow cushion for property taxes, and the buyer usually prepays the first year of insurance. Property taxes are prorated between buyer and seller at closing. These aren’t fees, but they do add to cash to close.

    Quick example: $400,000 Fort Lauderdale/Broward home, 80% loan

    ItemTypically paid byApprox.
    Deed doc stamps ($0.70/$100)Seller$2,800
    Mortgage doc stamps ($0.35/$100 on $320k)Buyer$1,120
    Intangible tax (0.2% on $320k)Buyer$640
    Owner’s title premium (promulgated)Varies by contract~$2,075
    Settlement/search fees, recording, lender’s policyBuyer/Sellervaries
    Lender fees, prepaids, escrowsBuyervaries

    The timing also matters. See How Long Does a Florida Closing Take? House vs. Condo.

    Get your exact Broward closing costs

    Skip the guesswork and start a closing cost quote using our TitleQuote calculator. You can also call Florida’s Best Title Company (Independent Title of Fort Lauderdale) at (954) 493-8288, 2881 E Oakland Park Blvd, Suite 302, Fort Lauderdale, FL 33306.

    FAQ

    How much are closing costs in Broward County for buyers?

    Usually about 2–5% of the purchase price. Financed buyers pay more because of mortgage doc stamps, intangible tax, and lender fees.

    How much do sellers pay in closing costs in Fort Lauderdale?

    About 1–3% before commission, mostly deed doc stamps at $0.70 per $100. With commission included, it’s roughly 6–10%.

    Who pays doc stamps on the deed in Broward County?

    The seller customarily pays deed doc stamps in Broward, though the contract controls.

    Is title insurance cheaper at a different title company in Florida?

    No. The premium is set by the state. Settlement and search fees do vary, so compare those.

    What is the intangible tax in Florida?

    It’s a one-time 0.2% tax on a new mortgage, normally paid by the borrower at closing.

    This article is for general information only and is not legal, tax, or financial advice. Rates and customs can change, and every transaction is different. Consult a Florida real estate attorney or tax professional about your situation.

  • You Can Choose Your Title Company in Florida (and Save Money on a Refinance)

    A lot of buyers and homeowners don’t know this: you usually get to pick your title company. It doesn’t have to be the one your lender, builder, or the other side suggests. Here’s why that choice matters and how it can lower your costs, especially on a refinance.

    You have the right to choose

    Under federal law (RESPA), a seller can’t require you to buy title insurance from a particular title company as a condition of the sale. On most mortgage loans, your Loan Estimate also has a section called “Services You Can Shop For,” and title services are usually listed there. A suggestion is just a suggestion.

    Why it matters who handles your closing

    Your title company does more than issue a policy. It:

    • Searches the public records and clears liens, judgments, and old mortgages
    • Orders estoppels and payoffs, and makes sure they’re paid at closing
    • Prepares the closing statement and handles your money in escrow
    • Records the deed and mortgage correctly

    A responsive title company that clears problems early is often the difference between closing on time and closing late.

    Where the money is on a refinance

    In Florida, the title insurance premium is set by state rule, so the premium itself is the same everywhere. The savings come from everything else:

    • Settlement and closing fees: These aren’t set by the state, and they vary from company to company.
    • Search and lien fees: Title search, municipal lien search, and other service charges also vary.
    • Reissue credit: If there’s a recent prior title policy on the property, you may qualify for a lower reissue rate on the new lender’s policy. Ask for it. Not every company checks unless you do.
    • No new owner’s policy needed: On a refinance, you normally only need a new lender’s policy. Your original owner’s policy keeps protecting you.

    On a refinance, the lender’s default title company may not have the lowest fees. One phone call and a quote comparison can put money back in your pocket.

    How to choose

    1. Ask for a written quote with every title and settlement fee listed, not just the premium.
    2. Compare line by line against the title charges on your Loan Estimate.
    3. Ask about the reissue rate if your property was insured recently.
    4. Ask who your closer is and how quickly they return calls and emails.
    5. Tell your lender early which title company you’ve chosen, so the file is opened right away. (See how long a Florida closing takes.)

    Bottom line

    Choosing your title company gives you control over service and fees. On a refinance, it’s one of the easiest ways to lower closing costs. You can start a closing cost quote from our homepage.

    Can I choose my own title company in Florida?

    Usually yes. A seller can’t require a particular title company as a condition of the sale, and title services are often listed as services you can shop for on your Loan Estimate.

    Do I need a new owner’s policy when I refinance?

    No. On a refinance, you normally only need a new lender’s policy.

    How can I save on title costs when refinancing?

    Compare settlement and search fees, and ask whether you qualify for a reissue rate.

    Are Florida title insurance premiums the same everywhere?

    Yes. The premium is set by state rule. Other title fees vary by company.

    When should I tell my lender which title company I chose?

    As early as possible, so the title work starts right away.

    This article is general information only and is not legal advice. Every transaction is different. For advice about your specific situation, talk with a Florida real estate attorney.

  • Double Closings in Florida: How a Same-Day A-B-C Closing Works

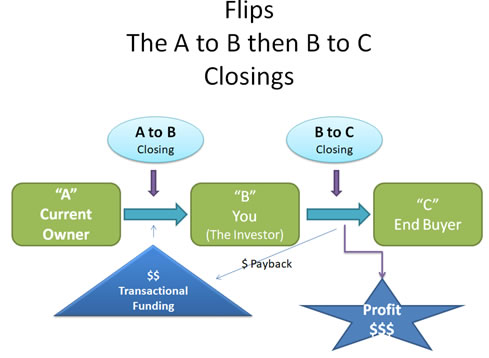
    In a double closing, an investor buys a property and resells it the same day. It’s common with wholesalers and flippers in South Florida. From the title side, it’s two closings that have to land in the right order.

    Who’s who

    • A is the original owner and seller.
    • B is the investor, who buys from A and sells to C.
    • C is the end buyer, who ends up owning the property.

    Two closings, one day

    A double closing is two separate transactions: A to B, then B to C. Each has its own closing statement, its own deed, and its own documentary stamp tax on the deed. Both deeds are recorded in order, so the public record shows A to B, then B to C.

    The funding question

    The A-to-B closing has to be paid for before B can sell to C. Many title companies won’t use C’s money to fund B’s purchase. B has to bring their own funds for the first leg.

    That’s where transactional funding comes in. A transactional lender sends money to the title company to fund the A-to-B purchase. Once everything is in place for both closings, they close back to back, the lender is paid back out of the B-to-C proceeds, and the investor keeps the spread. The loan is usually outstanding only for hours, so approval is based on the deal itself, not on B’s credit or income.

    Florida double closing diagram: A to B closing funded by transactional funding, then B to C closing with payback and investor profit.

    What the title company needs

    • Signed paperwork and clear title for both legs
    • Funds for A to B confirmed in escrow before anything is disbursed
    • C’s funds or loan ready to close the same day
    • Estoppels, payoffs, and lien searches cleared up front, just as with any closing

    Things that can slow it down

    • C’s lender: Some loans, including FHA, have rules about a property that was just bought. Check that C’s financing works with a same-day resale.
    • Open title issues: A lien or estate problem on A’s side stops both closings, not just one.
    • Association approval: In a condo or HOA, both B and C may need approval or an estoppel. Plan for it early.

    Bottom line

    A double closing works when the funds, the paperwork, and the title for both legs are ready before closing day. Bring the title company in early, and line up transactional funding if you don’t want to tie up your own cash. You can see how that funding works at Quick Transactional Funding.

    Related reading: Florida title insurance explained, how long a Florida closing takes, and association estoppel.

    What is a double closing?

    Two back-to-back closings on the same property, A to B and then B to C, usually on the same day.

    Can the end buyer’s money fund the investor’s purchase?

    Many title companies won’t allow it, so the investor brings their own funds or uses transactional funding.

    What is transactional funding?

    Short-term money sent to the title company to fund the A-to-B purchase, repaid from the B-to-C proceeds.

    Are doc stamps paid twice?

    Yes. Each deed is a separate conveyance with its own documentary stamp tax.

    Can the end buyer use an FHA loan?

    Sometimes not, because FHA restricts recently purchased properties. Check with the lender early.

    This article is general information only and is not legal advice. Every transaction is different. For advice about your specific situation, talk with a Florida real estate attorney.

  • Florida Title Insurance, Explained: What You’re Paying For at Closing

    Every Florida closing statement has a line for title insurance, and plenty of buyers sign without knowing what it does. Here’s the plain version.

    What title insurance protects

    Title insurance covers problems with ownership that come from the past, before you bought. Some examples:

    • A forged signature or fraudulent deed earlier in the chain of title
    • An heir or ex-spouse who never signed off on a prior sale
    • A recording or indexing error at the clerk’s office
    • A lien or judgment the search should have caught
    • A deed that wasn’t signed, witnessed, or notarized correctly

    If one of these shows up later, the policy pays to defend your title in court and covers your covered loss, up to the policy amount.

    Owner’s policy vs. lender’s policy

    There are two policies, and they protect different people.

    • Lender’s policy: Required if you have a mortgage. It protects the bank’s loan, not you, and it shrinks as the loan is paid down.
    • Owner’s policy: Protects you. You pay one premium at closing, and coverage lasts as long as you or your heirs own the property.

    Cash buyers don’t need a lender’s policy, but the owner’s policy matters just as much for them.

    Why the price is the same everywhere in Florida

    Florida sets title insurance premiums by state rule, based on the purchase price or loan amount. Every title company and underwriter charges the same premium for the same coverage. What can vary from company to company are the other title charges, like the settlement fee, title search, and municipal lien search. Compare those line items when you shop.

    Who usually pays

    It depends on the county. In Broward and Miami-Dade, the buyer customarily pays for the owner’s policy and chooses the title company. In Palm Beach and most other Florida counties, the seller customarily pays. Custom isn’t law, so it can be different in any given deal.

    What it does not cover

    • Anything listed as an exception in the commitment (Schedule B), like recorded easements or HOA restrictions
    • Zoning and building code issues
    • Problems a survey would have shown, unless survey coverage was added
    • Problems that start after you close

    That’s why reading the title commitment before closing matters. If an exception looks odd, ask about it before closing day, not after.

    Endorsements

    Lenders often require add-ons called endorsements, such as coverage for condos, planned communities, or survey matters. Each one has its own state-set charge and shows up as its own line on the closing statement.

    Why it feels expensive

    Most of what you pay for happens before closing: the search, the exam, clearing old liens and open estates, and getting the right signatures. Title insurance mostly works by finding and fixing problems up front, so fewer claims ever come up. The policy is the backstop for what no search can catch, like a well-done forgery.

    Bottom line

    The premium is set by the state, so focus on the title company’s service, its other fees, and whether it actually clears problems before closing day. If you want a number, our closing-cost estimate shows the title premium for your price.

    Related reading: how long a Florida closing takes, what title can and can’t fix at the walk-through, and HOA and condo estoppel.

    Is title insurance required in Florida?

    A lender’s policy is required with a mortgage. An owner’s policy is optional but strongly recommended, including for cash buyers.

    Who pays for title insurance in Florida?

    By custom, the buyer pays in Broward and Miami-Dade, and the seller pays in Palm Beach and most other counties.

    Are title insurance rates the same at every Florida title company?

    Yes. The premium is set by state rule. Other title fees can vary.

    How long does an owner’s policy last?

    As long as you or your heirs own the property, for one premium paid at closing.

    What doesn’t title insurance cover?

    Listed exceptions, zoning issues, survey matters without survey coverage, and problems that start after closing.

    This article is general information only and is not legal advice. Every transaction is different. For advice about your specific situation, talk with a Florida real estate attorney.

  • Closing-Day Walk-Through Discoveries: What Title Can (and Can’t) Fix That Day

    The final walk-through is usually the last time the buyer sees the house before they own it. Most of the time it is quiet: the sellers are out, the appliances are still there, and the place looks like it did when the offer was written. Sometimes it is not quiet. A fixture is gone. A wall is damaged. The garage remote is missing. The seller left a pile of junk in the lanai.

    When that happens, everyone looks at the title company. Here is what we can usually do on closing day in Florida, and what we cannot.

    What the walk-through is for

    The walk-through is a condition check, not a new inspection. Buyers are confirming that the property is in substantially the same condition as when the contract was signed, that items that were supposed to stay are still there, and that the seller has vacated (or will vacate on the agreed terms).

    Title is not inspecting the roof or the A/C. We are waiting to hear whether the deal is still on track to fund and record.

    Problems title can often help with that day

    • Holdbacks. If both sides agree in writing, we can hold a fixed amount in escrow after closing for a repair, a missing item, or a cleanup. That only works when the amount, the reason, and the release conditions are clear. Vague “we’ll figure it out later” holdbacks create fights.
    • Credits on the settlement statement. If the parties agree to a seller credit before documents are final, we can usually re-run the numbers the same day. On a financed deal, the lender may need to re-approve the Closing Disclosure, which can push funding past that afternoon.
    • Delaying funding (not just signing). Sometimes everyone signs, but we wait to fund until a property is delivered as expected, junk is removed, or a repair photo lands. That only works if the lender and wire timing allow it.
    • Possession and key logistics. We can coordinate key release with the parties’ instructions once funds are in and recording is set. We cannot invent a possession plan the contract never addressed.

    Problems title usually cannot fix that day

    • A brand-new major defect. A leaking roof discovered at 10 a.m. is not something title “clears.” That is a deal decision between buyer, seller, and their agents (and often the lender).
    • Missing personal property that was never on the contract. If it was not listed as included, title has nothing to enforce from the settlement statement alone.
    • Verbal promises. “The seller said they’d leave the TV mount” does not move money or delay recording unless it becomes a written instruction both sides sign.
    • Rewriting ownership or title exceptions. Walk-through issues almost never change the legal description, vesting, or title commitment. Those are separate problems.
    • Same-day magic on a lender CD change. Federal timing rules still apply. A last-minute credit can mean a new Closing Disclosure and a new waiting period.

    What slows a South Florida closing when a walk-through goes sideways

    The common pattern: discovery at morning walk-through → scramble to agree on a dollar amount → revised settlement statement → lender re-disclosure → afternoon funds do not hit → recording slips to the next business day.

    Cash deals have more flexibility on timing. Financed deals do not. If your closing is late in the day and the buyer is using a mortgage, leave less room for a surprise holdback.

    How agents can keep the day on track

    • Do the walk-through early, not an hour before signing.
    • Put any credit or holdback in writing before you ask title to change the statement.
    • Tell the title team as soon as something is wrong — not after everyone is already in the conference room.
    • Bring photos. A clear photo of the missing fridge or the damaged wall saves an hour of phone tag.
    • Know whether the lender will allow a same-day CD change before you promise the buyer they will still get keys that afternoon.

    What Independent Title needs from you

    If a walk-through issue is going to change money, possession, or timing, send us the written agreement and the exact numbers. We will update the settlement statement, confirm whether the lender needs a new disclosure, and tell you honestly whether same-day funding is still realistic.

    Independent Title of Fort Lauderdale (Florida’s Best Title Company) closes files across Broward, Palm Beach, and Miami-Dade. Call (954) 493-8288 or email info@indytitleftl.com.

    This article is general information about typical Florida closing logistics, not legal advice. Your contract and lender instructions control your file.

    Related reading